Francis Wade | The hidden bets your company makes
Loading article...
-
 Photo - AG Guest Guest
-
Photo - AG Guest Guest
-
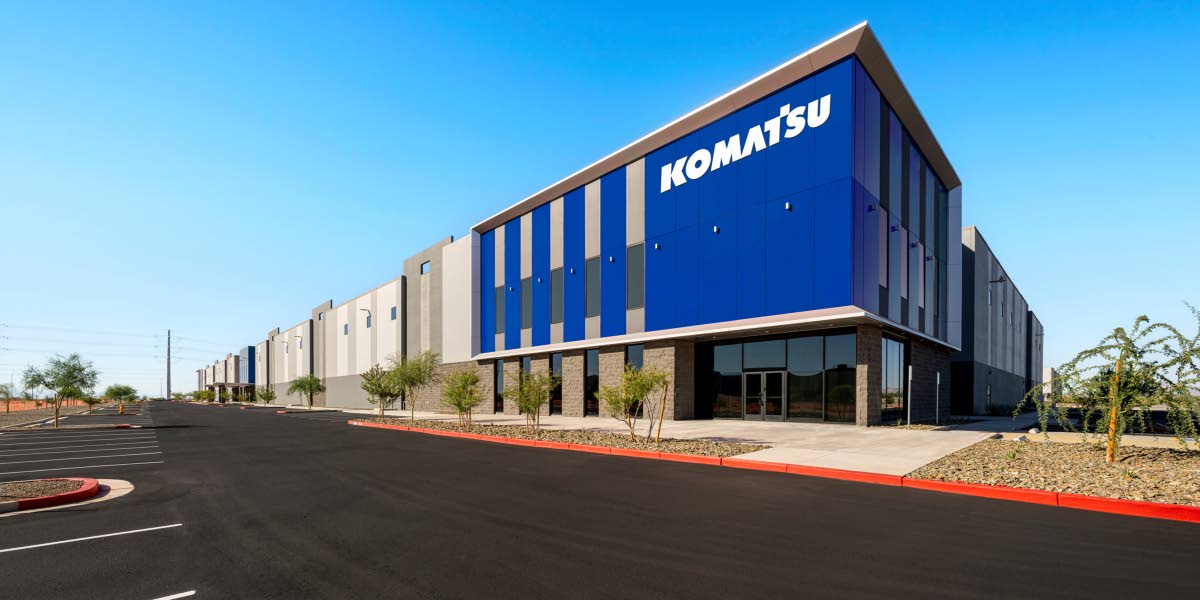 The Komatsu facility. AP
-
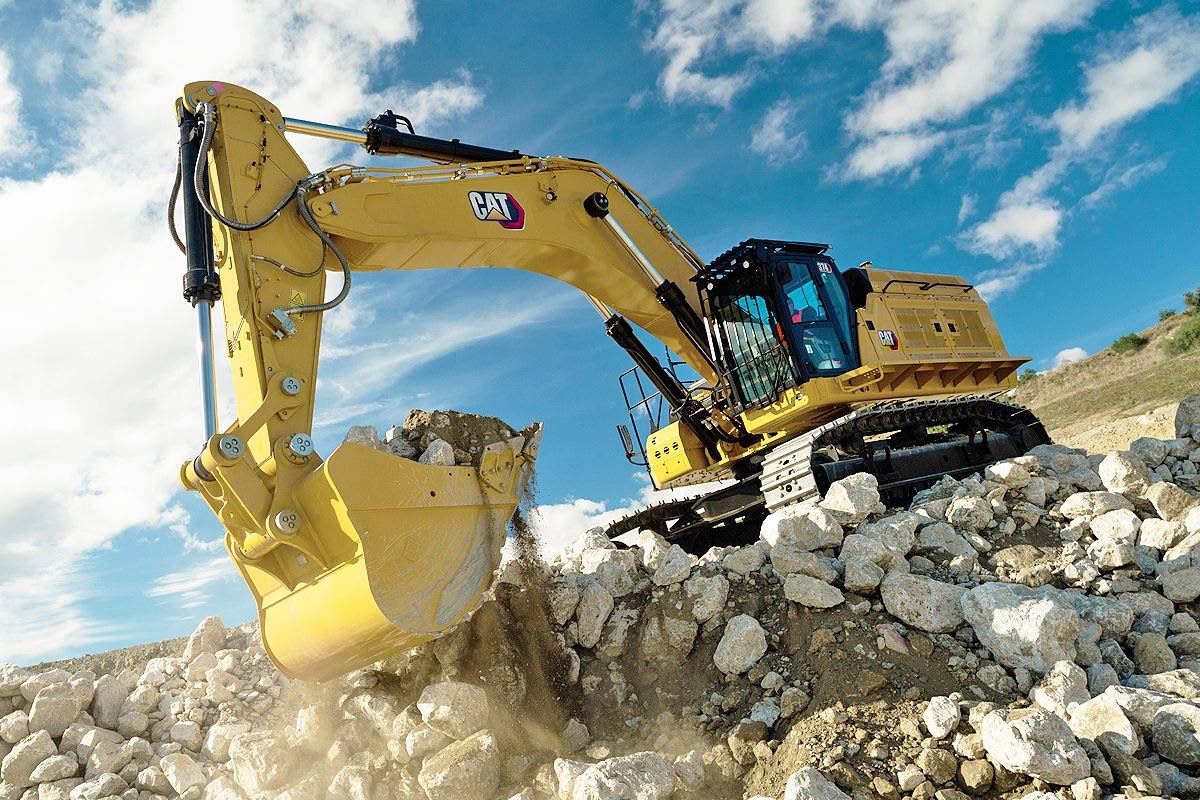 A Catapillar Cat 374 Hydraulic excavator.
Imagine that your company proclaims its intent to ‘be number one’. The objective is clear, but you suspect that a commitment this simple may create more problems than it solves. If so, how should you proceed?
In 2021, I wrote a Gleaner column on the reasons why company visions that promise dominance, first-place, or top-of-the-charts performance tend to fail. Such statements persist. The chest-beating I described then is the lesser concern, because a larger problem sits underneath it.
Proponents of such goals argue that stakeholders need something simple to focus on. But the challenge is that the simplification collapses several commitments into one. A realistic list of commitments is a diverse one: profit (or a non-profit surplus), customer value, staff commitment, resilience, innovation, social impact, and survival or longevity. A ‘number one’ goal reduces that list to a single item.
Komatsu, the Japanese heavy-equipment maker and rival to Caterpillar, shows what that costs.
From the 1960s to the 1980s, Komatsu’s stated strategic intent was “to encircle Caterpillar”. Gary Hamel and C.K. Prahalad popularised the slogan, and business school professors still teach it as an example of bold goal-setting. It was more than words. Each year, Komatsu’s priorities and projects were faithfully modelled on Caterpillar’s performance.
While the global market was growing, the goal worked. But worldwide growth in heavy equipment fell. By the late 1980s, Komatsu’s growth and profits had stagnated, and its dependence on construction equipment and on Japanese markets had become increasingly problematic.
In 1989, new President Tetsuya Katada concluded that the initial, bold aspiration to beat Caterpillar ended up being constraining. Managers had grown accustomed to operating within a single defined objective and struggled to innovate when growth stalled.
To force managers to question what the company should become, Katada replaced the old goal with a deliberately broad one: “Growth, Global, Groupwide”. The phrase was then turned into specific, fresh opportunities and outcomes.
Komatsu’s history includes two stated bets. The first gamble, to focus on beating Caterpillar, was explicit. The second, Katada’s broader goals, followed once the first proved insufficient in a changed context.
‘Number one’ visions tend to follow this pattern. They make one bet explicit and leave the rest implicit.
An ‘explicit bet’ is an outcome a company states. An ‘implicit bet’ is any other commitment that the stated outcome compresses, such as customer value or resilience, which the company quietly trades away. For example, at Komatsu, one casualty was managers’ freedom to question direction. Trading it away did not pay off: over time, managers lost the capability.
But it gets worse. A third kind of bet is harder to find than the other two because it never appears in the strategic plan at all.
SHADOW BETS
Implicit bets can be found by asking what a goal leaves out. ‘Shadow bets’ resist that test because nobody realises they are making them.
A shadow bet is an outcome a company commits to through repeated choices, omissions, and budget decisions, without ever stating it. A staff poll will rarely surface one, so it has to be inferred from behaviour.
In the Komatsu case, the company made a shadow bet on continued, consistent growth. Its annual priorities and projects, all pegged to Caterpillar’s results, implied that growth would continue, whether anyone said so or not.
Shadow bets are hard to avoid because every organisation acts on assumptions it never examines. For example, many companies today are shadow betting that climate change will not affect their operations. That assumption may hold in the short term. Behind it sits a second shadow bet: that future leadership teams will be able to handle the fallout of climate change in the mid to long term.
Shallow strategic analysis enables shadow bets, which multiply in companies that limit their thinking to mere five-year horizons. However, firms that practise rigorous strategic foresight make fewer shadow bets, and the ones they make carry less risks.
MAKING SHADOW BETS VISIBLE
Take these three questions into your next leadership meeting.
. Explicit bets: What are we betting on?
. Implicit bets: Which other commitments does this goal compress, and what does that cost us?
. Shadow bets: What hidden wagers do our budgets, promotions, and omissions imply? An outside facilitator or LLM can help here because neither is invested in our stated intentions.
Start with your own ‘be number one’ goal. List what it states, what it compresses, and what your budgets quietly indicate. The gaps between those three lists show where the unexamined risk sits.
A company places its bets every year through what it funds, whom it promotes, and what it leaves unfunded. Ask the three questions, and you may find a number of bets nobody decided to make.
Francis Wade is the author of Perfect Time-Based Productivity, a keynote speaker and a management consultant. To search his prior columns on productivity, strategy, engagement and business processes, send email to columns@fwconsulting.com.